
- Buy and hold investing mistakes to avoid: costs, emotions
- What passive investing actually means
- Why trading has to clear a cost hurdle
- Why emotional investing feels like a plan
- Passive does not mean set-and-forget
- Check the benchmark and product design
- A special caution about used and inverse ETFs
- Questions to ask before acting
Buy and hold investing mistakes to avoid: costs, emotions
One of the most expensive investing habits can look responsible in the moment: trading every time a headline changes, a market dips, or prices rally. For households balancing rent or mortgage payments, family expenses, and shifting goals, these passive investing mistakes can make a long-term strategy harder to follow.
Passive, or buy-and-hold, investing is a less hands-on approach that aims to follow market performance over time, often through index funds and relatively few trades. It does not guarantee returns or prevent losses. It is a framework to understand, not a recommendation for how any particular person should structure an account.
Before changing an investment, it helps to ask three basic questions: What is the product designed to do? What does it cost? Has something meaningful changed, or does the decision simply respond to an uncomfortable day in the market? FINRA explains that a passive approach can help investors avoid fear of missing out, panic during volatility, and impulse buying or selling.
What passive investing actually means
Passive investing aims to recreate market performance over time rather than exceed it. Investors commonly use index funds, which seek to follow a particular market index. Index funds can also help spread exposure across multiple investments instead of placing the entire result on one security.
Active investing takes a different route. Active investors or managers may buy and sell more often, adjust a portfolio on short notice, and try to exceed market performance by responding to short-term conditions or individual opportunities. Both approaches can involve individual securities, mutual funds, or exchange-traded funds, so a product’s name alone does not tell the whole story.
“Buy and hold” also does not mean holding exactly the same investments forever. A fund can change its focus or composition, and an index fund can adjust as companies are added to or removed from its underlying index. The investor may make relatively few discretionary trades while the fund continues to follow its stated strategy.
The person making the decisions is a separate question. An investor can manage an active or passive approach independently or work with an investment professional. The fund itself is managed by an investment adviser that follows either an active or passive strategy. Active versus passive investing describes the strategy, not whether the account is self-directed.
That makes “boring” useful shorthand, but not a complete description. The approach involves less day-to-day intervention by the investor, not total inactivity or neglect.
Why trading has to clear a cost hurdle
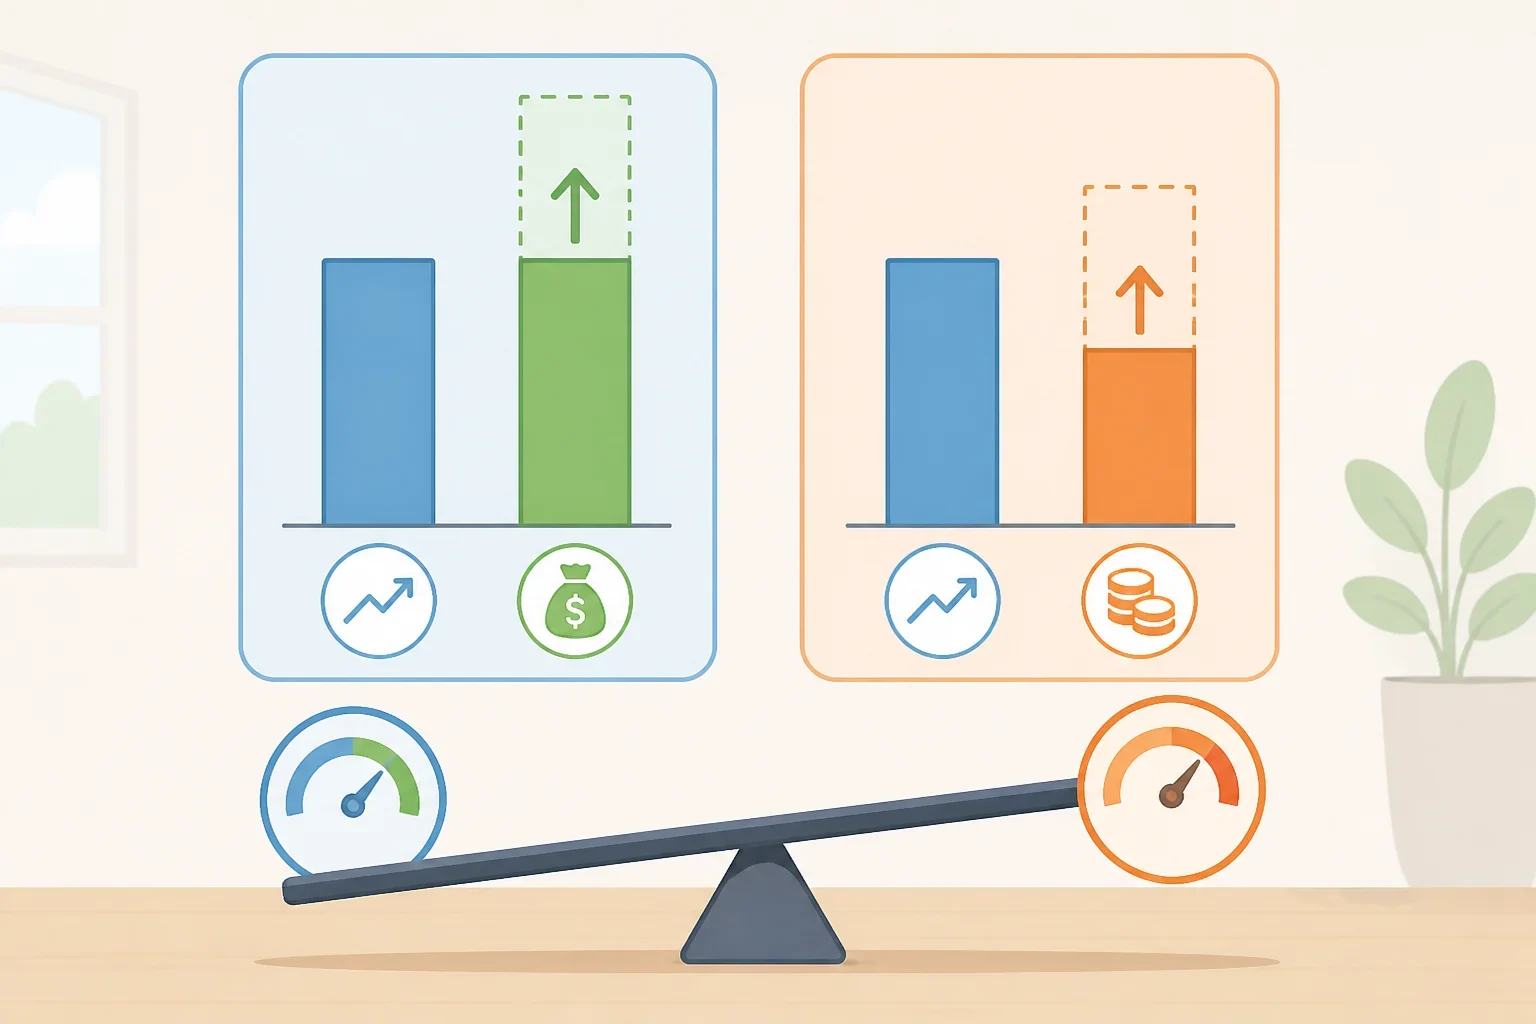
Trading and investment products can carry costs such as bid-ask spreads, markups or markdowns, sales loads, management fees, and other expenses. The exact costs depend on the product and transaction, so checking the fee information before choosing an investment matters.
A lower-activity approach may involve fewer transaction and management fees, but that does not make every passive product inexpensive or every active product unsuitable. The narrower point is more useful: a trade needs to produce enough benefit to outweigh the costs of acting.
Fund expenses make that hurdle easier to see. Suppose an actively managed fund charges 1.5% in management and administrative fees while its benchmark returns 9%. The fund would need to return more than 10.5% before fees to beat that benchmark, according to FINRA’s benchmark guide. Anything below that level would leave the fund behind the benchmark after those fees.
That example does not prove that active managers cannot outperform, and it does not establish that passive investing will always perform better. It shows how costs affect the return a fund must generate before investors see an advantage over a comparison index.
Fewer transactions can potentially make taxes less complicated for passive investors, although the details depend on the account, investment, and transaction. That general point should not be treated as individualized tax guidance.
A trade also has a timing problem. Being directionally right is not enough if the move is too small, too brief, or too costly to overcome the expenses attached to buying and selling. The more often a person acts, the more often that hurdle appears.
Why emotional investing feels like a plan
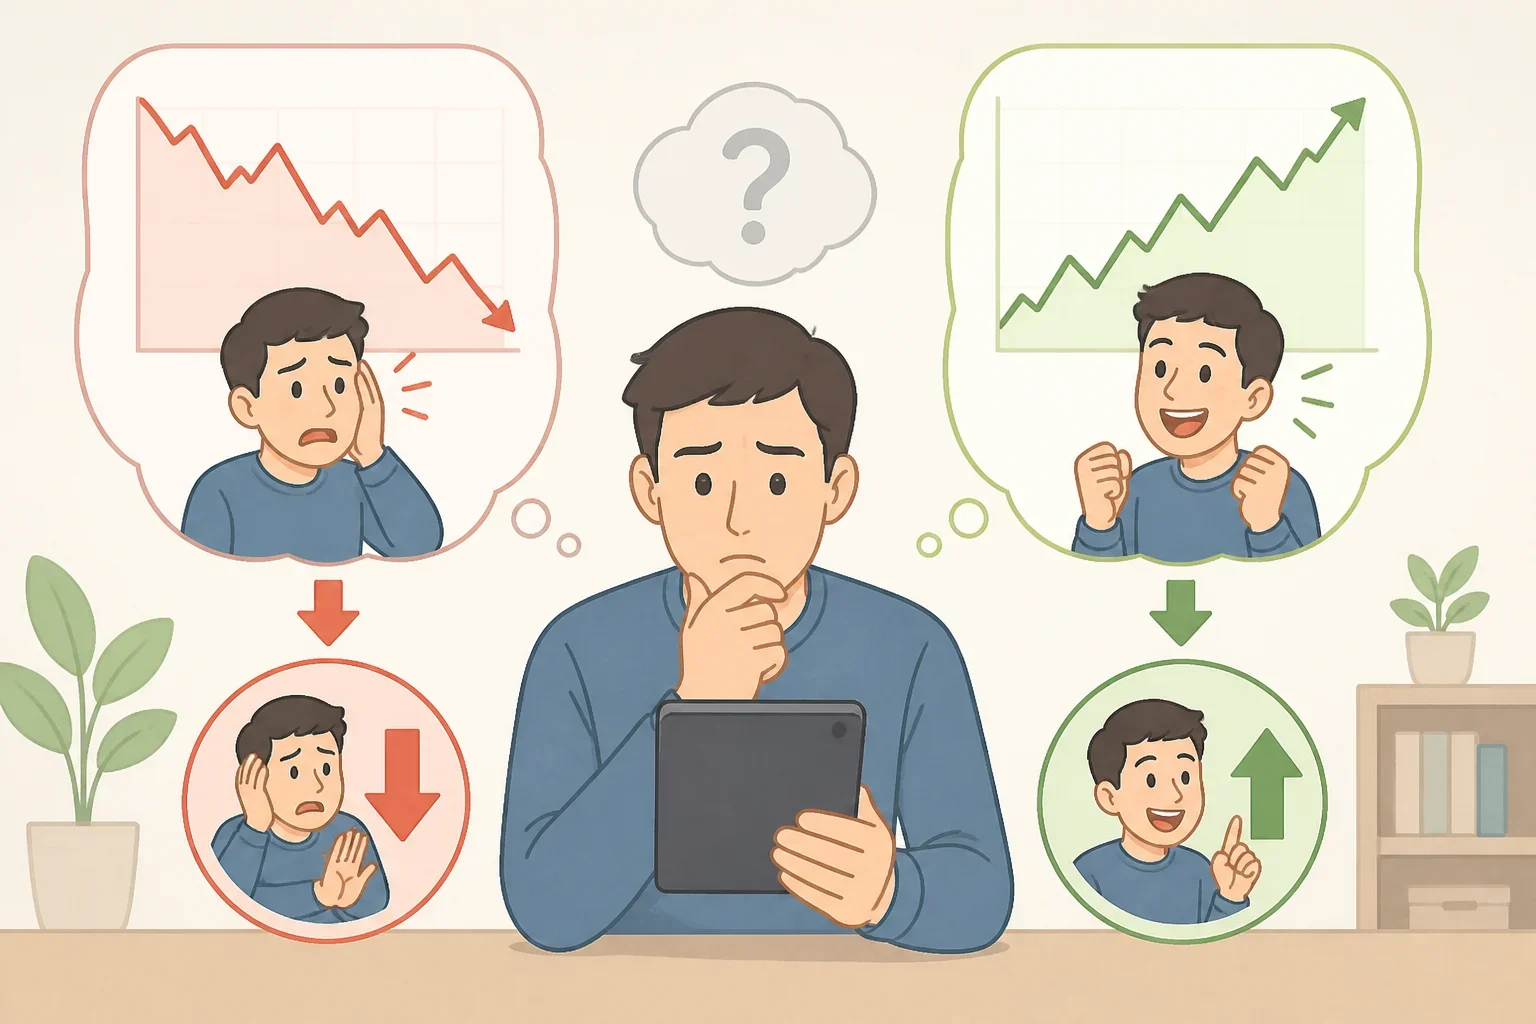
Costs are only part of the problem. The other part is the feeling that doing something is safer than waiting.
A rising market can trigger fear of missing out. A falling market can make selling feel like a responsible act of protection. A passive strategy can help investors avoid impulse purchases or abandoning positions during market increases or declines that may prove temporary.
That does not mean emotions are irrational in every situation. A change in household circumstances may justify a careful review. The problem is treating every market move as evidence that a previously considered strategy is wrong.
Early success can make that reaction stronger. In the theoretical model described in “Learning to Be Overconfident”, economist Terrance Odean explores how traders may take too much credit for successful outcomes and become overconfident. The model suggests that overconfidence is greatest early in a trading career, while expected trading activity can rise and expected profits can fall as traders overestimate their ability.
This is a model, not a direct measurement of every individual investor’s behavior. It still offers a useful explanation for why a few successful trades can feel like proof of skill. A person may remember the correct call more clearly than the uncertainty surrounding it.
A low-activity strategy does not eliminate that temptation. It creates fewer built-in opportunities to act on it. That can make a plan easier to follow, but only if the investor understands the plan before a volatile day arrives.
Passive does not mean set-and-forget
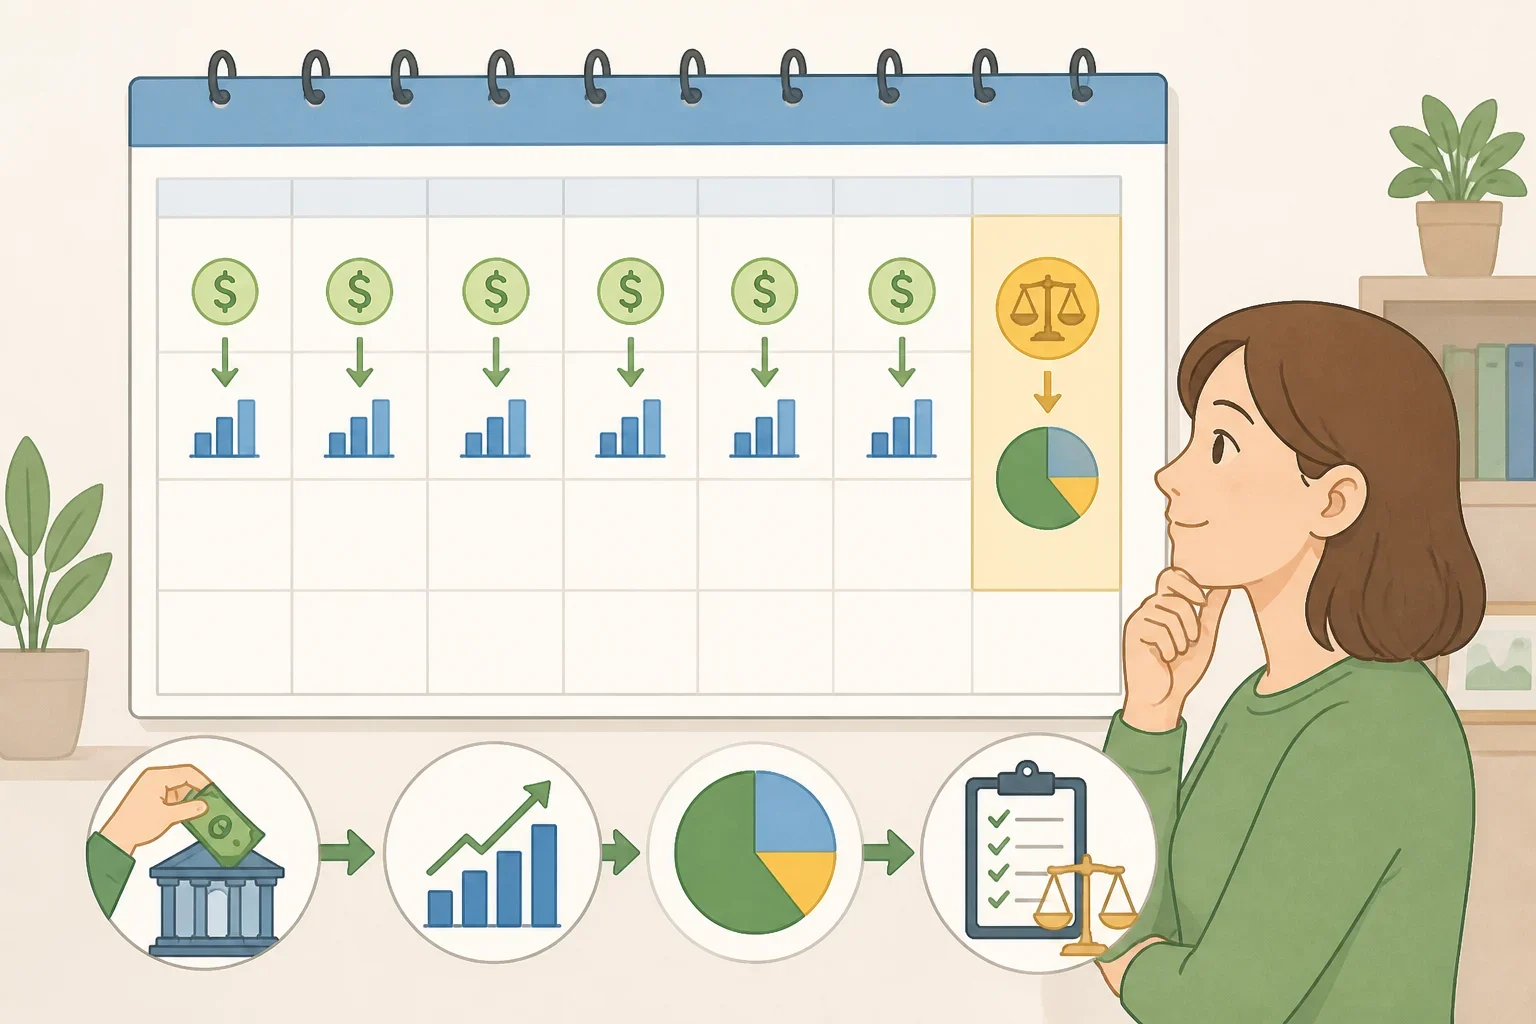
A passive strategy can include structure. FINRA describes periodic investing as making fixed-dollar purchases on a set schedule. It also describes scheduling a date, such as an annual review, to rebalance a portfolio toward a desired asset mix when investments no longer move together.
Those are concepts, not universal instructions. The useful distinction is between a scheduled review and a reaction to a market headline. One follows a defined process. The other may be an improvised response to fear, excitement, or a news cycle that has not changed the investment’s stated objective.
Index funds can provide diversification, but the label should not end the review. A fund may track a narrow segment of the market, while a model portfolio tracking multiple indexes may provide additional diversification. The product’s holdings, objective, fees, and benchmark still matter.
A “set-and-forget” mindset can also miss changes in a fund or in an investor’s circumstances. Buy and hold is not the same as never reading a fund report, checking its objective, or reconsidering whether the original circumstances still apply. It means the decision to act should have a reason beyond the market moving today.
Check the benchmark and product design
A benchmark is a standard used to compare an investment’s past performance. The comparison only helps when the benchmark is relevant to the investment being assessed.
For example, FINRA identifies the S&P 500 as a possible benchmark for a large-capitalization U.S. stock fund and the Russell 2000 as a possible benchmark for a U.S. small-cap fund. A fund’s report may identify the index it uses and show how its performance compares.
A single quarter, or even a single year, can be distorted by one-time events. FINRA recommends comparing performance across several years, while also warning that past benchmark performance does not guarantee future results. The question is not simply, “Did this fund go up?” It is, “What does this fund seek to track, and how did it compare with an appropriate standard over a meaningful period?”
The same care applies to the product itself. An exchange-traded fund may look familiar because it trades on an exchange, but its objective can be very different from that of a traditional index fund.
A special caution about used and inverse ETFs
used and inverse ETFs are designed around daily performance objectives. A used ETF may seek a multiple of an index’s daily return, while an inverse ETF may seek the opposite of that daily return. Most reset daily.
Over weeks, months, or years, the result can differ significantly from the stated multiple or inverse of the underlying index’s performance. The effect can become more pronounced in volatile markets. In one example from the SEC’s investor bulletin, an index fell 1% over two days while a 2x used ETF fell 4%, even though the fund produced twice the index’s daily return on each of those two days.
The example is not a prediction for every used ETF. It shows why a daily objective should not be confused with a longer-term buy-and-hold objective. The SEC says these specialized products generally are not suitable for buy-and-hold investors, and notes that used or inverse ETFs may be more costly and less tax-efficient than traditional ETFs.
Before considering one, read the prospectus. It contains information about the fund’s investment objective, strategies, risks, and costs. A reader also needs to understand what happens if the product is held for longer than one trading day.
Questions to ask before acting
These are educational questions, not instructions to buy, sell, rebalance, or change a portfolio:
- What strategy does the fund actually follow?
- What index or benchmark is it designed to track?
- What fees and expenses does it charge?
- Does the product aim to reflect daily performance or longer-term exposure?
- Does the prospectus explain used or inverse exposure and daily resets?
- Is the decision responding to a temporary market move or to a previously defined plan?
- Has a genuine change in circumstances occurred, or has the investment simply become uncomfortable?
For fee comparisons, readers can also review FINRA’s Fund Analyzer. Questions about portfolio structure, risk, account type, or tax circumstances belong with a qualified investment professional.
The practical lesson is modest: before responding to market news, check whether anything has changed about the fund’s objective, benchmark, costs, product design, or the circumstances behind the original decision. If none of those has changed, pausing may be more informative than trading.
