
- Lending Money to a Family Member: The Decision and Conversation That Matter Most
- Start with the household’s real comfort level
- Choose the arrangement before the transfer
- Put expectations into plain words
- Treat repeated requests as a change in the conversation
- Know when the conversation needs professional help
Lending Money to a Family Member: The Decision and Conversation That Matter Most
When a family member asks for money, the first decision is not how quickly to transfer it or when repayment should begin. It is whether the help will be a gift, a genuine loan, or a respectful no with another kind of support offered instead.
That choice needs to be clear before money changes hands. One relative may hear, “This will help until things settle down,” while the other is thinking, “The money will come back soon.” If neither says what the arrangement means, a short-term favor can become a recurring source of tension.
Parents helping adult children is common enough to be part of the ordinary ways money moves between generations, according to the Pew Research Center. But common does not mean simple. This is a relationship and communication guide, not tax, estate, mortgage, business, or legal advice. The IRS gift tax guidance and IRS Applicable Federal Rates are starting points for questions about transfers and loans, not substitutes for individualized advice.
When property, business funding, estate plans, or complicated repayment terms enter the picture, the family conversation should make room for a qualified professional.
Start with the household’s real comfort level
Before answering the relative, the person giving the money needs an honest conversation with any spouse or partner whose household resources are involved.
A useful question is: If the money never comes back, could the household accept that without needing the money for an important expense?
This is a personal risk check, not a technical financial standard. It cannot predict what will happen. It simply brings the uncomfortable possibility into the open. Even a sincere plan to repay can change when employment, housing, health, or another household responsibility changes.
Look at the request in practical terms:
- Would providing the money affect bills, housing costs, food, insurance, or another necessary expense?
- Is the money coming from a shared account?
- Does the spouse or partner understand the amount and the proposed arrangement?
- Would saying yes create resentment if repayment were delayed?
- Would the household feel pressured to provide more later?
A private promise made with shared money can create conflict between partners, even when both care about the relative asking for help. That conversation belongs at home before the answer goes back to the family member.
Emotional capacity matters, too. A person may be able to give the money but still feel unable to handle reminders, missed payments, or repeated requests. That does not make the person uncaring. It may mean the arrangement needs clearer limits, or that cash is not the right form of help.
Choose the arrangement before the transfer
For many families, the practical choices are a gift, a loan, or a decline. None is automatically generous or selfish. The responsible choice is the one that matches what the giver can actually offer and what the recipient understands.
The gift-versus-loan distinction also matters beyond the relationship. The IRS treats money given without an expectation of repayment differently from money intended to be paid back. If the amount or circumstances raise tax questions, the family should pause and ask a qualified professional rather than rely on an informal label.
If it is a gift
A gift means the recipient is not being asked to repay the money. The giver can explain what the money is intended to cover and whether additional help is possible, but repayment cannot remain a private condition.
A clear script might be:
“This is a gift. You do not need to pay it back. We can help this one time, but we cannot promise future financial help.”
That last sentence prevents a one-time gift from sounding like the beginning of an ongoing arrangement. It gives the recipient useful information without turning the conversation into a warning.
A gift is not a loan with a softer name. If the giver expects repayment, even informally, that expectation needs to be addressed honestly. Hidden conditions are difficult for the recipient to meet and difficult for the giver to enforce without damaging trust.
It is also worth considering whether the gift could affect future family conversations. Financial support between parents and adult children can happen more than once, and a first gift may shape what relatives expect later. A family does not need to promise identical help to everyone, but it should be honest about whether this is a one-time decision or part of a larger pattern.
If it is a loan
A loan means both people genuinely expect repayment. That expectation should not exist only in the giver’s head.
Before agreeing, discuss the basic understanding in ordinary language:
- What problem is the money meant to address?
- Is the full amount expected back?
- When does the recipient believe repayment could begin?
- What should happen if the original plan changes?
- How will the family talk about a missed or delayed payment?
- Does the arrangement need to be shared with a spouse, partner, or anyone else affected by it?
These questions are not a loan contract, and they do not answer tax or legal questions. They are a way to find out whether both relatives mean the same thing when they say “loan.”
If the conversation becomes vague whenever repayment comes up, that is useful information. The arrangement may be closer to a gift, a partial gift, or a request the household should decline. It is better to recognize that before the transfer than after the first missed payment.
A simple script is:
“We are considering lending this amount, but repayment needs to be part of the agreement. We need to make sure we both understand what that means before any money is transferred.”
For arrangements involving repayment terms, interest, property, a business, or a substantial transfer, the IRS’s published interest benchmarks may be one topic to raise with a CPA or attorney. The IRS Applicable Federal Rates page does not decide whether a specific family arrangement is appropriate or how it should be documented.
If the answer is no
A decline can be kind and direct. It may mean the household cannot take on the financial or emotional obligation, not that the relative’s problem is unimportant.
Another form of help could include:
- listening and helping the relative think through options
- reviewing a plan without providing money
- offering time or practical assistance
- making a connection to a relevant organization or professional
- giving a smaller amount only if it can genuinely be treated as a gift
The alternative should be manageable. Offering help the household cannot sustain only delays the difficult conversation.
Try:
“We cannot provide the amount you asked for, and we do not want to promise money we may need ourselves. We can help you think through other options.”
If a smaller gift is possible, say what it is without presenting it as a loan:
“We cannot make a loan, but we can give this smaller amount with no expectation that it comes back.”
“Not right now” can sound compassionate, but it may also leave the door open to the same request later. If the answer is no, clarity is kinder than an accidental promise.
Put expectations into plain words
The important conversation does not need to feel like a business meeting. It does need to happen before the transfer, when both people can still make a choice.
Financial education organizations emphasize clear communication around family support, especially when people may have different assumptions about what the money means. The National Endowment for Financial Education also points to the tension that can arise when one relative receives help and others compare that support with their own treatment.
Questions that may help include:
- “What would this money solve?”
- “Are you asking for a gift or a loan?”
- “What are you expecting from us?”
- “What are we actually able to offer?”
- “If repayment becomes difficult, how should we talk about it?”
- “Could this affect future requests for help?”
- “Who needs to know because shared household money is involved?”
The goal is not to demand every detail of the relative’s private life. It is to make sure the giver and recipient are answering the same question.
Privacy may need its own conversation. The recipient may not want other relatives to know. The giver may need to discuss the decision with a spouse or partner, particularly when shared money is involved. If the family is also thinking about future gifts or an estate, keeping the arrangement entirely private may make later conversations harder. That is a family communication concern, not a statement about legal disclosure requirements.
Fairness can be complicated. Different relatives may have different needs, and a family may choose to help one person in a particular situation without making identical promises to everyone else. Still, it is worth considering what the decision could communicate.
A sentence such as this can set a boundary:
“This help is connected to this specific situation. It does not mean the same arrangement will be available to everyone or that we can continue it indefinitely.”
That explanation cannot guarantee that nobody will feel disappointed. It does give the family a clearer understanding of what the decision means.
Treat repeated requests as a change in the conversation
A one-time request and an ongoing pattern are different household decisions. If new requests arrive before the earlier arrangement is resolved, the family may need to stop discussing each amount separately and decide what role it is willing to play.
Signs that the original understanding needs to be revisited can include:
- repayment is repeatedly postponed without a new conversation
- another request arrives before the earlier one is resolved
- the giver feels unable to ask about the money
- the recipient treats future help as already promised
- a spouse or partner is becoming resentful
- relatives are arguing about secrecy, favoritism, or future plans
- the money is being used for a different purpose than the one discussed
These signs do not prove bad intentions. They indicate that the arrangement may no longer match what either person originally understood.
A calm boundary might sound like this:
“We are not able to provide additional money while the earlier arrangement is unresolved. We need to pause and decide what, if anything, we can offer from here.”
The boundary should match what the household can maintain. A limit that cannot be kept may create more confusion, while a clear and consistent answer gives everyone better information about the next step.
Know when the conversation needs professional help
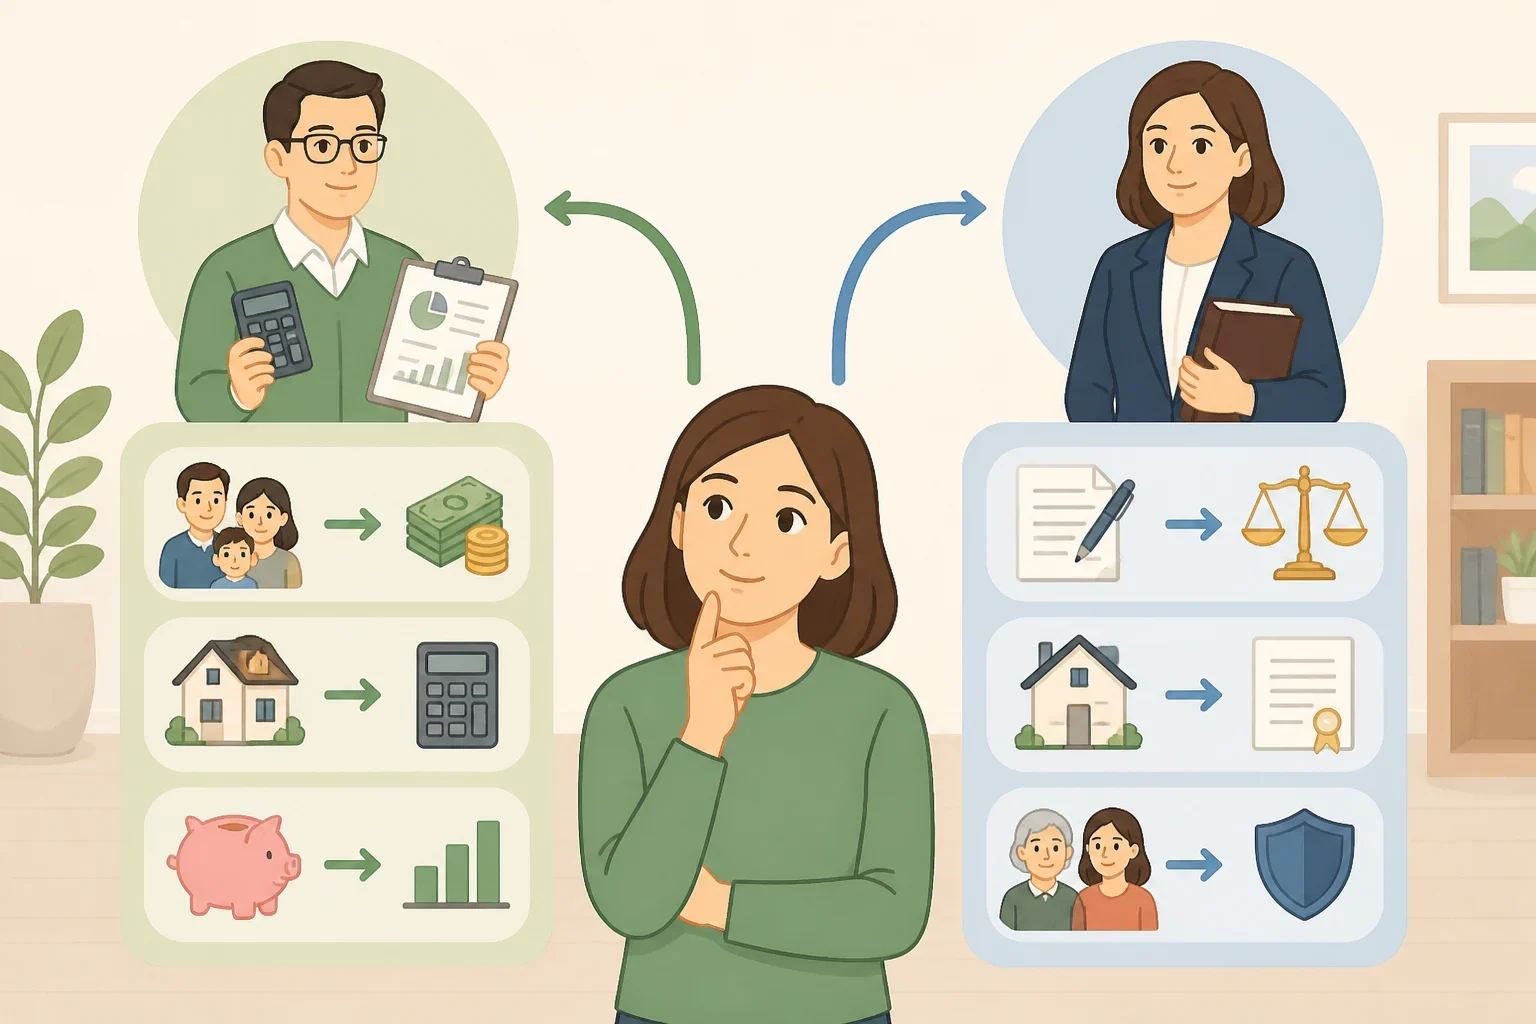
Some family money questions are too consequential to settle informally. The need for advice depends on the amount, the parties’ circumstances, the proposed repayment terms, whether property or a business is involved, and whether the transfer could affect an estate or future inheritance.
That does not mean every small gift requires formal planning. It does mean that a family should pause when the arrangement has consequences beyond the immediate relationship.
Consider asking a qualified professional before money moves if the request involves:
- a home purchase or shared property
- a business investment or ownership interest
- repayment terms or interest
- repeated lending
- disagreement about whether the money is a gift or a loan
- possible effects on an estate or future inheritance
- tax questions that cannot be answered from general information
A CPA may be appropriate for questions about tax treatment. An estate attorney may be appropriate for inheritance or estate-planning concerns. The specific professional should match the question. A mortgage or business professional may help with a property or company transaction, but that does not automatically make that person qualified to advise on tax or estate consequences.
The family’s role is not to create technical terms from a template or assume that “just between relatives” removes the need for care. It is to describe the situation accurately, agree on what communication is needed, and seek the right help when the decision has moved beyond a simple household conversation.
Before answering a family member, pause long enough to align with any spouse or partner whose resources are involved. Decide what is genuinely being offered. Say whether it is a gift, a loan, or a decline, and do not leave repayment expectations hidden between the lines.
If the request includes property, business funding, recurring lending, estate concerns, or complicated terms, stop treating it as an informal favor and ask a qualified professional about the specific issue. Clear communication may not make the decision easy, but it can keep a difficult money conversation from becoming an even more difficult family one.
