
- October 15 tax extension deadline: What to do now
- When is the October 15 tax extension deadline, and who does it apply to?
- Does the tax extension filing deadline give you more time to pay?
- How to file taxes by October 15
- What happens if you miss the October 15 tax deadline?
- Your three-step plan for today
October 15 tax extension deadline: What to do now
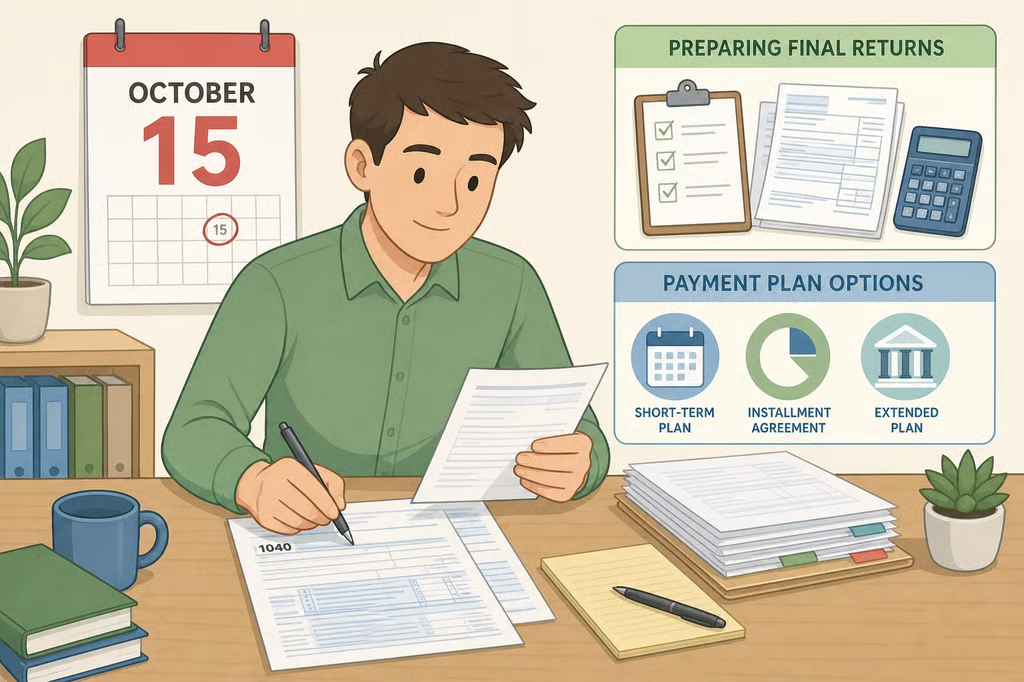
As of October 6, the October 15 tax extension deadline is nine days away. For individual taxpayers with a valid federal extension, October 15 is generally the last day to file without the failure-to-file penalty that can apply after an extended deadline. The extension does not give extra time to pay a federal tax balance. Taxes owed under the standard individual deadline were still due April 15, 2026, and interest and penalties can accrue after that date. The IRS explains that an extension applies to filing, not payment.
If a full payment is not ready, file the return anyway, pay what is available, and consider a payment plan for the remaining balance. If a refund is expected, filing is still necessary before the IRS can issue it. The steps below can help organize the final push without waiting for every question or document to be perfectly settled.
When is the October 15 tax extension deadline, and who does it apply to?
October 15 generally applies to individual taxpayers who requested a six-month extension by the regular filing due date. An individual can request that extension by filing Form 4868, Application for Automatic Extension of Time To File U.S. Individual Income Tax Return. The Taxpayer Advocate Service explains that an electronic payment made by the original due date can also serve as an automatic extension request, so not everyone who has an extension will have a Form 4868 confirmation.
This rule covers the individual federal return, including a self-employed person who reports business income on Form 1040. It does not mean every business return is due October 15. Businesses generally use Form 7004, and the extension period can vary by entity type.
October 15 is not a universal deadline, either. U.S. citizens and resident aliens who live abroad may receive an automatic two-month extension to file and pay, generally until June 15, with the option to request another four months by filing Form 4868. That overseas rule differs from the standard extension, which usually adds time to file but not time to pay. For taxpayers abroad who do not pay in full by the two-month date, penalties and interest are assessed from that date rather than April 15.
Military members serving in a combat zone and taxpayers in areas covered by a disaster declaration may also have automatic relief or a different deadline. The IRS’s individual tax filing guidance says disaster-affected taxpayers may have more time to file. Check the specific relief that applies before assuming October 15 is the correct date.
Once the correct deadline is clear, the next question is the one that affects the household budget most: Does the tax extension filing deadline give you more time to pay?
Does the tax extension filing deadline give you more time to pay?
No. For most individual taxpayers, the extension moves the filing date, not the payment date. A balance due under the standard rules was due April 15, 2026, even if the taxpayer received more time to submit the return.
Interest and late-payment penalties generally begin after the payment due date. Payments made after that date can continue to accrue interest and penalties until the balance is paid, subject to the limits allowed by law. The Taxpayer Advocate Service says paying sooner can reduce the additional interest and penalties that build on the unpaid amount.
That creates two separate problems:
- Failure to file: A penalty may apply when the return is filed after the applicable deadline.
- Failure to pay: Interest and a late-payment penalty may apply to an unpaid tax balance after the payment due date.
A filing extension may help with the first problem, but it does not erase the second. Some penalties can be abated in certain circumstances, including situations where the taxpayer can establish reasonable cause. Interest generally is not waived except in limited circumstances, such as an IRS-caused delay.
If the return shows a balance due, do not hold the return until the entire amount is available. File, pay as much as possible, and review payment-plan options for what remains. The Taxpayer Advocate Service advises taxpayers who cannot pay in full to file and pay what they can rather than leaving the account unaddressed.
How to file taxes by October 15
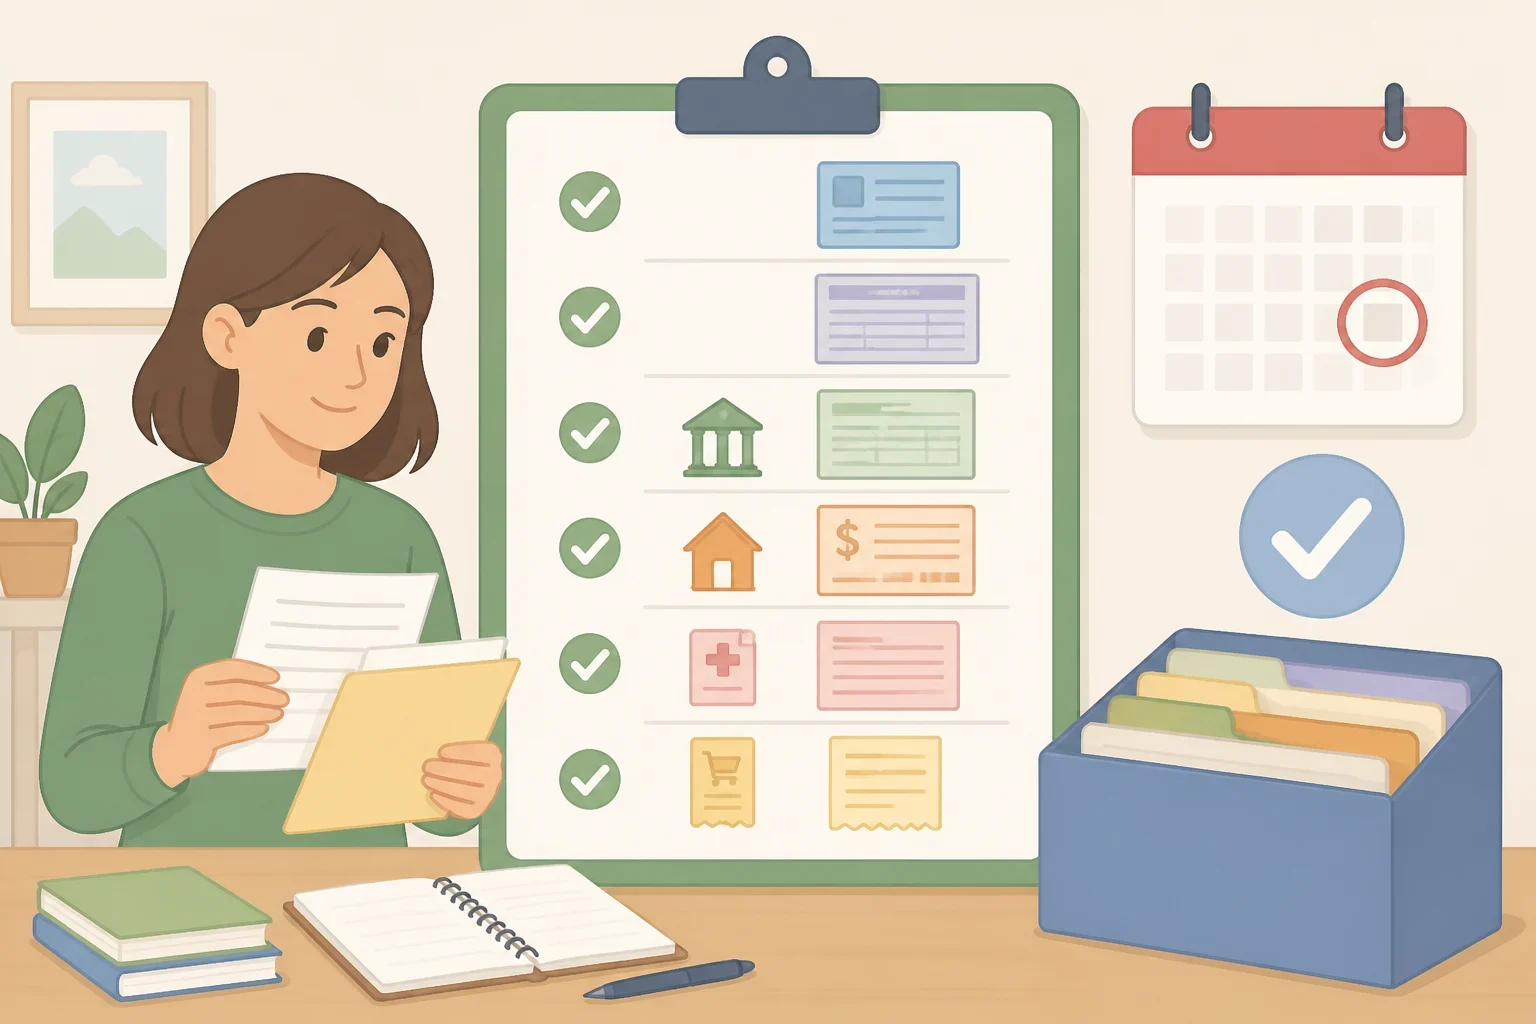
Set aside the documents and account information needed to finish the federal return:
- The Form 4868 acknowledgment, confirmation number, or proof of mailing, if you used that route
- The electronic payment confirmation, if the payment itself created the extension
- W-2s, 1099s, and other income records
- Deduction and credit records needed for the return
- Access to tax software or another filing method
- Bank information for a payment or refund, if applicable
Then work through this sequence.
1. Locate the extension confirmation
Look for the electronic acknowledgment or confirmation number from the extension filing. If Form 4868 was mailed, find the proof of mailing. If an electronic payment created the extension, locate the payment record.
The documentation does not replace the return. It simply gives you a record of how and when the extension was requested. Keep it with the tax records in case proof is needed later. The Taxpayer Advocate Service’s extension guidance identifies an electronic confirmation or certified mailing receipt as useful documentation.
If no confirmation can be found, do not assume the extension failed or succeeded. Gather the available payment or mailing information and continue preparing the return. A tax professional may be able to help sort out a missing record.
2. Gather the missing income documents
Make a short list of anything still needed, such as an income form, account statement, or record supporting a deduction or credit. Contact the employer, financial institution, or other issuer if a document is missing.
Do not invent a figure simply to finish faster. If the missing record affects income, withholding, or a major deduction, use the time available to verify it. The goal is a complete return, not merely a submitted one.
3. File the federal return
Use electronic filing if it is available for the return and situation. Before submitting, check names, Social Security numbers, bank details, income, withholding, and the extension information. A small data-entry mistake can create a larger cleanup job later.
Submit the return as soon as it is ready rather than waiting for October 15 itself. The IRS says an extension gives eligible taxpayers until October 15 to file without the failure-to-file penalty, but the return still has to reach the IRS. For a refund, the Taxpayer Advocate Service notes that the return is not considered filed until the IRS, not the Taxpayer Advocate Service, receives it.
4. If you owe money, pay what is available
Make a payment with the filing if possible, even if it covers only part of the balance. Reducing the unpaid amount can reduce the interest and penalties that continue to accrue.
Then review the IRS payment-plan options for the remainder. A payment plan does not change the original payment due date or automatically remove charges already assessed, but it gives the unpaid balance a formal path forward. If a notice has already arrived, follow the instructions on that notice and keep copies of payments and correspondence.
If the balance is unexpected or substantially different from the estimate used for the extension, check the return before paying. Confirm that withholding, estimated payments, credits, and deductions were entered correctly. When the numbers remain unclear, ask a qualified tax professional for help.
5. If you expect a refund, file anyway
A refund cannot be issued before the IRS receives the return. Filing sooner starts the process; waiting until the deadline only delays that submission.
A refund may also be affected by an eligible debt submitted through the Treasury Offset Program. The Taxpayer Advocate Service says taxpayers can contact the agency connected to the debt or call the Bureau of the Fiscal Service at 800-304-3107, or TTY/TDD 800-877-8339, Monday through Friday from 7:30 a.m. to 5 p.m. CST, to ask whether a debt was submitted for offset.
Anyone experiencing financial hardship and considering an Offset Bypass Refund should contact the IRS at 800-829-1040 or the Taxpayer Advocate Service before filing the return with the IRS. The source notes that there is no specific form used to request an OBR.
6. Check the state return separately
Federal and state filing rules are separate. A federal extension may not settle the state filing deadline, payment requirement, or extension process.
Check the state tax agency’s website for the return deadline and payment instructions. If the state return is due on a different date, add it to the household calendar now. Do not assume that submitting the federal return also submits a state return.
What happens if you miss the October 15 tax deadline?
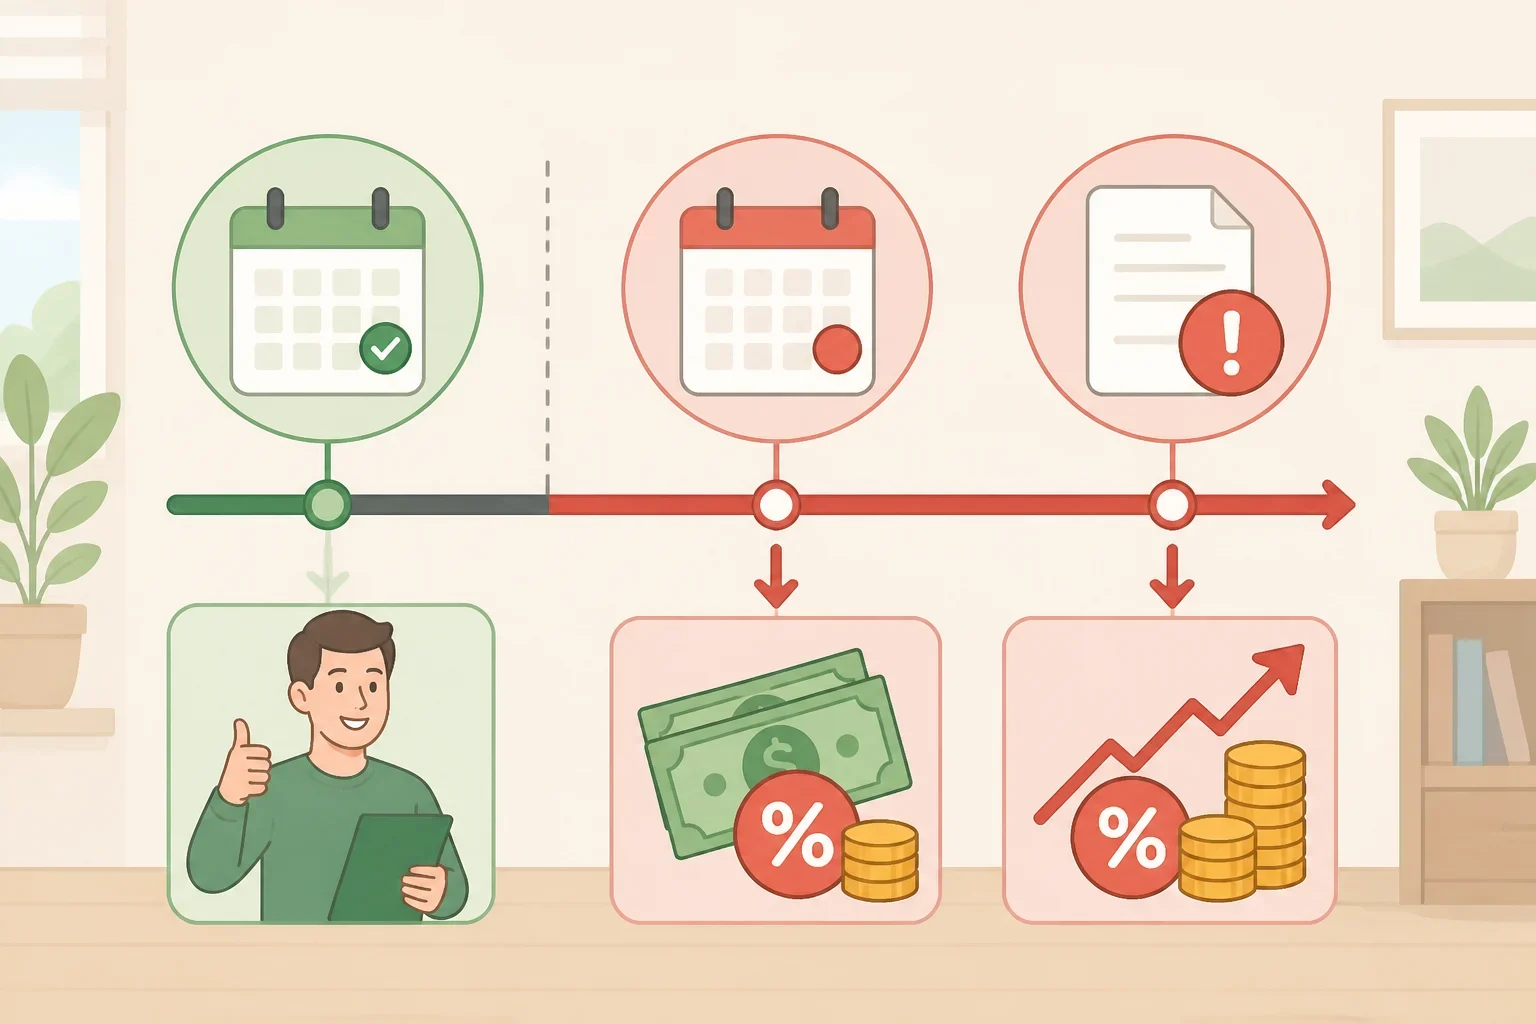
If October 15 applies and the federal return is filed after that date, the IRS may assess a failure-to-file penalty. The size and application of any penalty depend on the taxpayer’s account and circumstances. If a reasonable cause prevented timely filing, the taxpayer may ask the IRS to abate the penalty and provide a written explanation of what prevented the filing.
A late return can also leave a balance due unresolved. Interest and the failure-to-pay penalty may continue while tax remains unpaid. Paying as soon as possible can limit additional charges, though it does not necessarily remove charges that have already accrued.
If no return is filed, the IRS may eventually prepare a Substitute for Return, or SFR. That return may not include deductions, credits, and exemptions the taxpayer could have claimed. The Taxpayer Advocate Service explains that filing an accurate return of your own can allow those items to be considered.
When an SFR or a taxpayer-filed return shows a balance due, the IRS may pursue collection. Depending on the situation, that can include a lien attached to property or property rights, or a levy on a bank account, wages, or another source of income.
A refund also has a filing deadline. Generally, a claim for credit or refund must be filed within three years of the original return filing date or two years from the date the tax was paid, whichever is later. Missing the applicable Refund Statute Expiration Date can mean losing the refund, so a late refund return should be filed rather than set aside.
Your three-step plan for today
- Find the extension record and finish the return. Use the acknowledgment, payment confirmation, or mailing proof to document the extension.
- Submit the federal return and pay what is available. If the balance is not fully covered, review payment-plan options instead of waiting.
- Save the confirmation and check the state deadline. Keep the federal submission record with the tax documents, then verify the separate state requirements.
If a different rule applies because of overseas residency, military service, or a disaster declaration, confirm that deadline before filing. Otherwise, eligible individual taxpayers should aim to have the federal return received by October 15, while treating the unpaid balance and any state filing as separate tasks.
